

MULTI-ASSET CLASS MONITOR HIGHLIGHTS
WEEK ENDED SEPTEMBER 25, 2026
Strong PMI data and Treasury buyback shortfall push yields higher
US Treasury yields rose across the curve in the week ending September 25, 2026, as a much stronger than expected flash PMI report and a shortfall in the Treasury's bond buyback program combined to push long-term borrowing costs to fresh multi-decade highs. The 10-year yield ended the week 16 basis points higher, while the 2-year yield climbed 7 basis points, leaving the 10s2s spread 9 basis points wider at 34 basis points.
Wednesday's move accounted for most of the increase, marking the steepest single-day rise in the 10-year yield since April 7, 2025, when borrowing costs skyrocketed in the wake of so-called Liberation Day. The trigger was the September flash PMI, which showed the composite index climbing to 58.4, its highest level in more than five years, with the services and manufacturing components both comfortably beating expectations. Input cost inflation also accelerated to its highest level since October 2022. Markets read the combination as reinforcing the case for further Fed tightening, raising the implied probability of an October rate hike to around 70%.
Most of the curve steepening happened on Thursday, when the 10-year yield rose another 9 basis points against 3 basis points for the 2-year benchmark. The underperformance of the long end was driven by another underwhelming buyback operation from the US Treasury. Having offered to purchase up to $6bn of long-dated debt, the department purchased just $4.08bn, an even larger shortfall than the $5.19bn bought in the first such operation on September 10. Both operations were followed by yields moving higher rather than lower, the opposite of their intended effect.
The steep rise in the 10-year yield also resulted in another widening of the corresponding real rate to 2.86% on Thursday, which constitutes its highest level since November 2008.
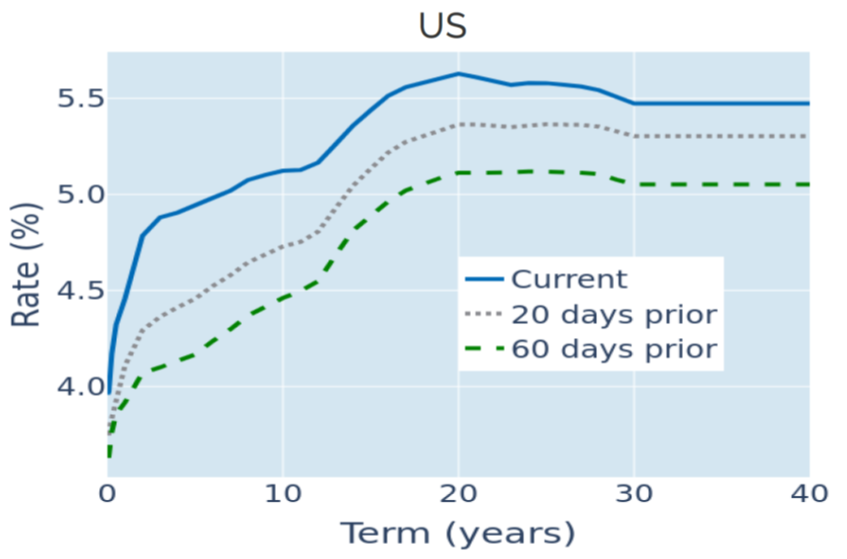
Please refer to Figure 3 of the current Multi-Asset Class Risk Monitor (dated September 25, 2026) for further details.
Dollar keeps rallying on higher rates as yen bucks the trend
The US dollar continued to benefit from last week’s rise in domestic interest rates, with most of the appreciation coinciding with Wednesday’s surge in Treasury yields. The Dollar Index gained 0.8% over the week, with the euro and pound weakening by 0.5% and 0.9%, respectively.
The only notable exception was once again the yen, which more than recouped all of its earlier losses on Friday, ending the week 0.2% in the black. The rally followed Finance Minister Satsuki Katayama's disclosure that President Trump had raised concerns over the yen's weakness during a summit with Prime Minister Sanae Takaichi in New York on Tuesday. Katayama added that she and US Treasury Secretary Scott Bessent will continue to communicate closely on foreign exchange, reaffirming the stance behind their July 31 coordinated intervention.
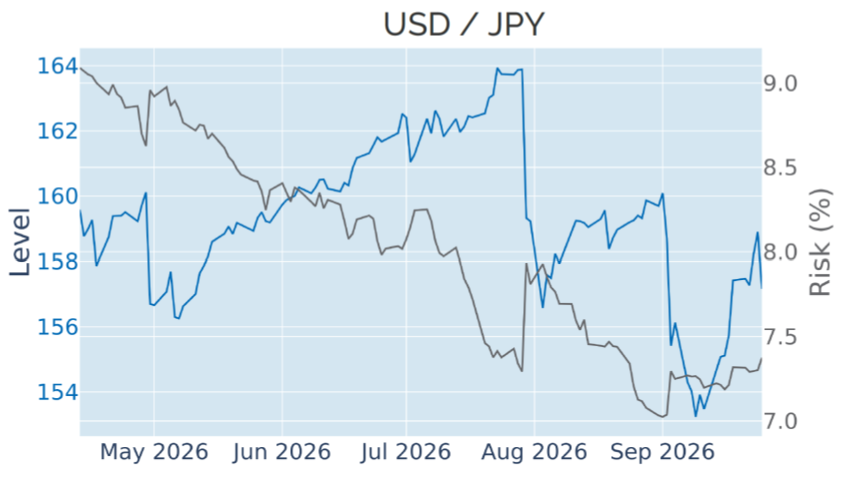
Please refer to Figure 6 of the current Multi-Asset Class Risk Monitor (dated September 25, 2026) for further details.
Higher equity and rate volatility push portfolio risk higher
Predicted short-term risk for the Axioma global multi-asset class model portfolio rebounded by 0.4 percentage points to 6.3% as of Friday, September 25, 2026, as standalone equity and interest rate volatilities both increased. The continued dollar strength alongside the ongoing rise in global yields also meant that bond returns and exchange rates against the dollar appeared more positively correlated. This effect was most notable for non-USD government bonds, whose share of total portfolio volatility expanded from 8.1% to 9.5%. US investment grade corporate bonds recorded an even bigger increase, with their percentage risk contribution climbing 1.9 percentage points to 6.4%, reflecting a double whammy of higher interest rate and credit spread volatility, as both widened together.
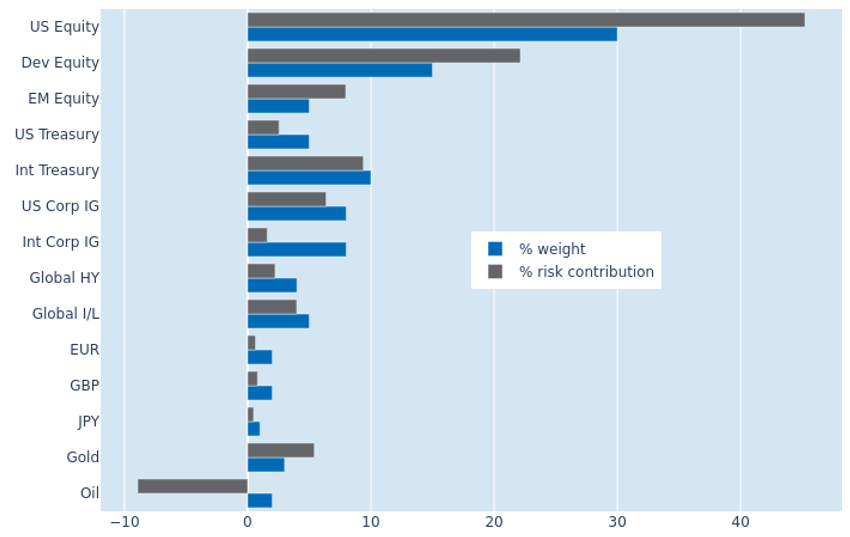
Please refer to Figures 7-10 of the current Multi-Asset Class Risk Monitor (dated September 25, 2026) for further details.
You may also like


