

EQUITY RISK MONITOR HIGHLIGHTS
WEEK ENDED OCTOBER 9, 2026
- US market strong on strong earnings expectations, as sector performance flipped from the prior week…
- …but breadth remains narrow, especially in the US
- The sectors with the best Momentum are shifting
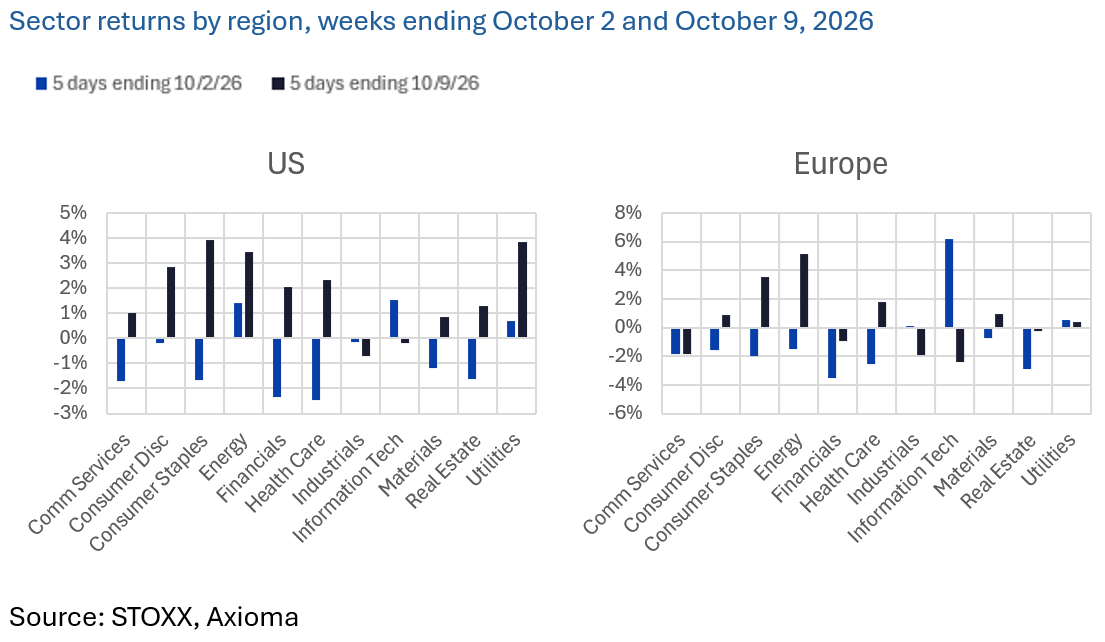
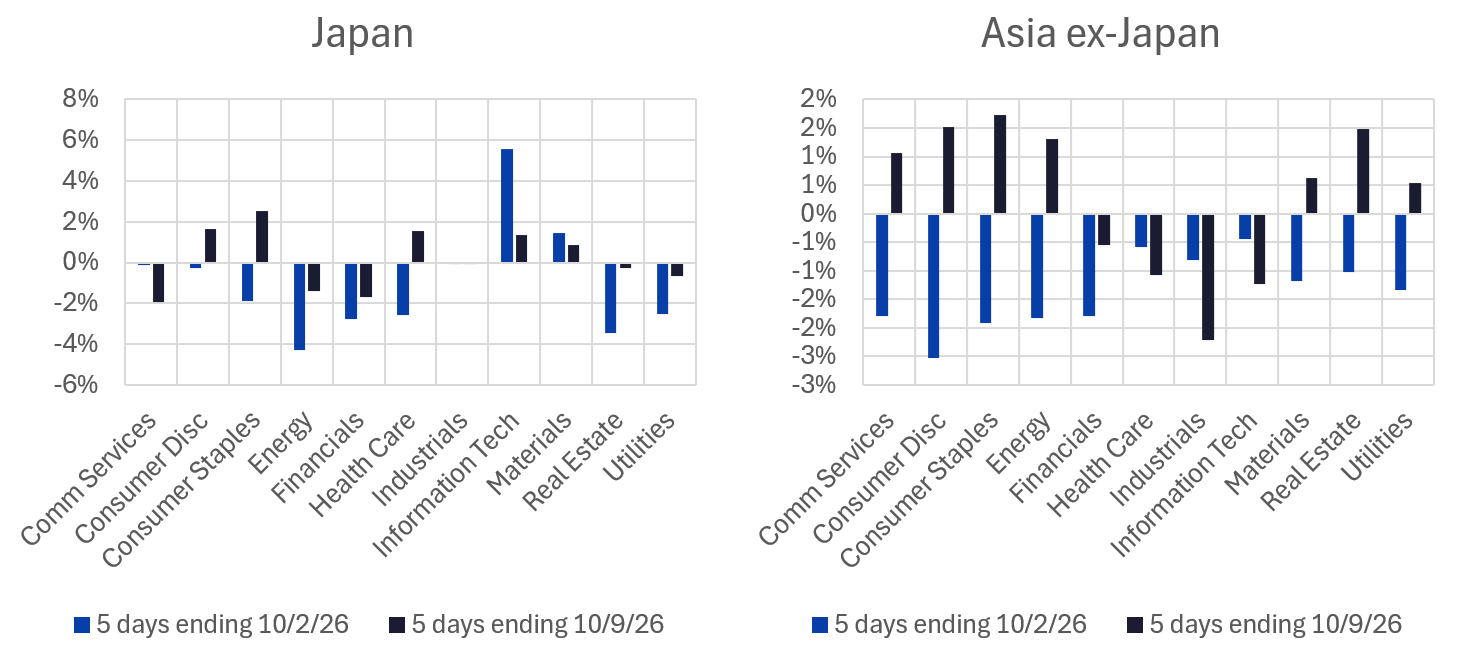
US market strong on strong earnings expectations, as sector performance flipped from the prior week
Despite rising oil prices, higher bond yields and continued inflation concerns, earnings expectations are propelling the market, and some US indices revisited all-time highs last week. While waiting for earnings season to start, investors in many markets were optimistic. According to FactSet, S&P 500 earnings growth for the third quarter versus Q3 2025 is expected to reach almost 30%, propelled by Industrials, Energy and Technology. That growth expectation has been revised up from earlier in the third quarter, and FactSet notes that earnings usually come in higher than expected, so the growth percentage could hit the mid-30s.
However, sector performance last week was quite different from that in the week prior, extending the trend of declining correlations that we have been writing about (see these recent highlights). The rotation also suggests that the market’s narrative may be changing and introducing volatility under the surface even as top-line risk remains low. See our recently-released quarterly risk review for more detailed analysis.
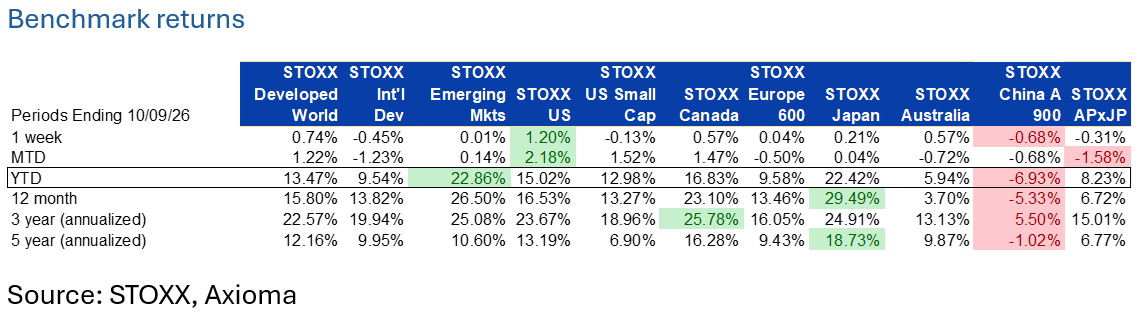
The following table and charts do not appear in the Equity Risk Monitors, but are available on request:
…but breadth remains narrow, especially in the US
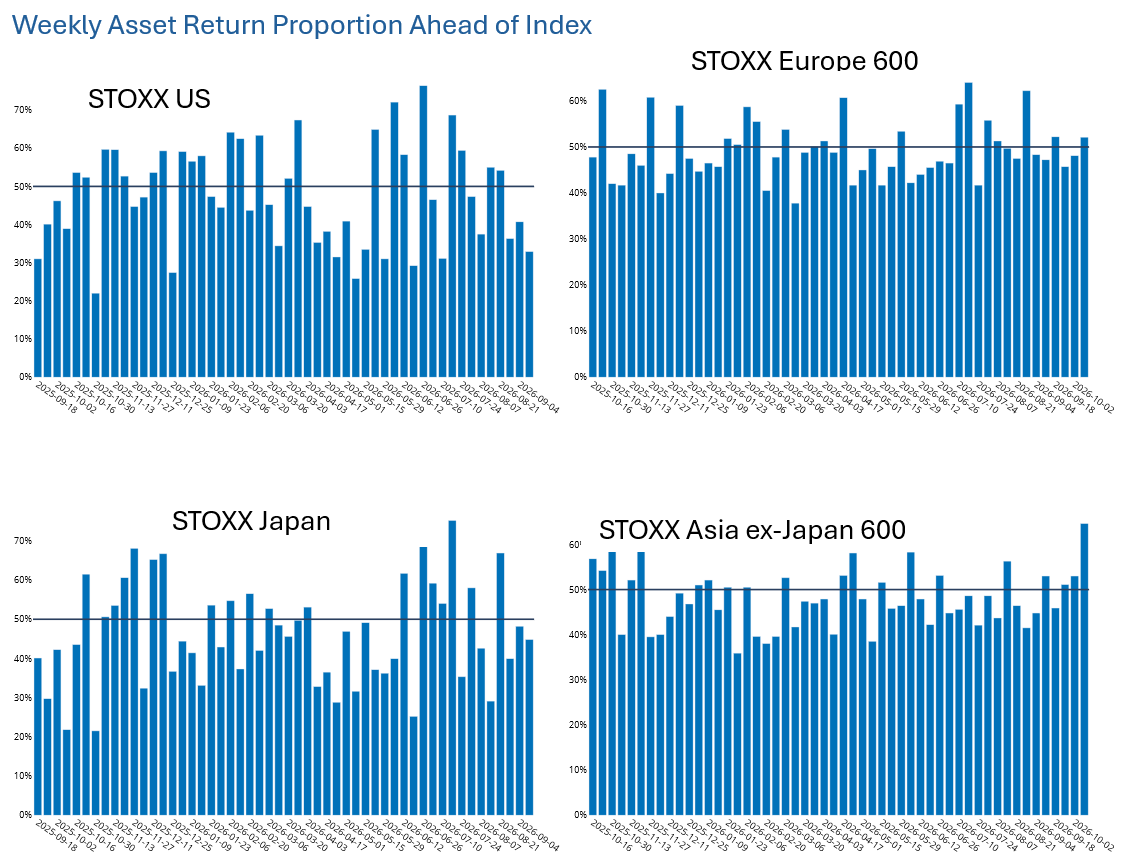
While the US market may have reached new highs last week, it did so with only slightly more than 30% of stocks in the index participating. This narrow breadth continues to exacerbate the disparity in returns between equally-weighted and capitalization-weighted index and suggests it is even tougher than usual to beat the US market. The Japanese market is facing a similar issue, with fewer than 50% of the stocks in the index faring better than the index most weeks, and seeing higher returns when the index is cap weighted. In contrast, returns in the European market as defined by the STOXX Europe 600 are roughly the same, whether cap- or equal-weighted. Here, just slightly more names underperform the index vs. outperforming.
See charts from the STOXX US, STOXX Europe 600, STOXX Japan and STOXX Asia ex-Japan Equity Risk Monitors as of October 9, 2026
The change in sector performance week-to-week also brings up the question of “where is the Momentum and has it changed”
The sectors with the best Momentum are shifting
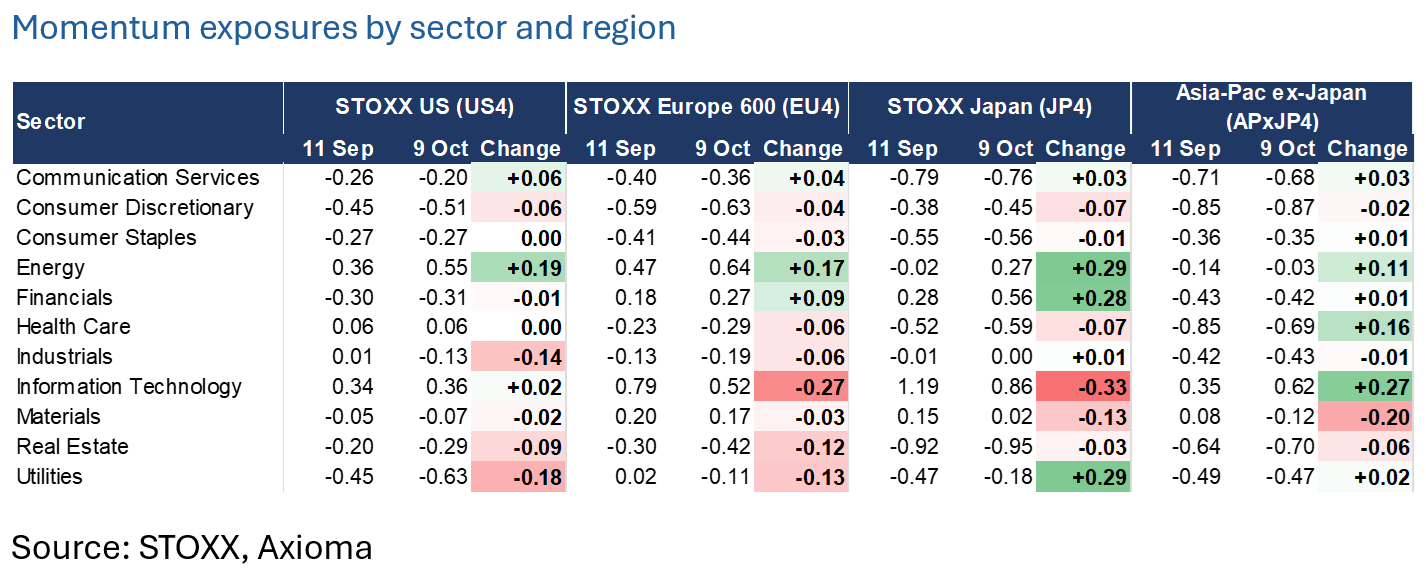
Spurred by the reversals in sector performance noted above, we compared the current Medium-Term Momentum exposures in the four major developed markets to those of a month ago. We observe some big changes, most notably in Japan.
Given the sustained increase in oil prices, it is not surprising that Energy’s momentum has improved across the board. Japan stands out because Energy’s Momentum exposure has gone from negative to positive. In the US and Europe the exposure was also positive last month, it has just gotten more so. In Asia ex-Japan, the exposure is currently higher than it was, although it remains just below zero.
The other sector with the biggest month-over-month change in exposure in more than one region is Information Technology. Here, the exposure has dropped substantially in Europe and Japan, although it remains highly positive in both. The Asia ex-Japan Tech's exposure to Momentum has increased (and don’t forget that the index we use is purely developed markets, and therefore excludes South Korea and Taiwan). In Emerging Markets (not shown), the exposure of Tech to Momentum remains higher than in any of the other indices we examined, although it has fallen a bit since mid-September. In addition, most changes in Emerging Markets sector Momentum exposures were quite small.
Financials’ Momentum exposure is negative in the US and Asia ex-Japan and has remained stable. It is positive and up slightly in Europe, but saw a big jump in Japan.
One other regional sector’ Momentum exposure is worth mentioning – Momentum for Utilities in Japan has improved by quite a bit, although it remains slightly negative as of the end of last week.
The following table summarizes what appears in the Equity Risk Monitors, and is available on request:
You may also like


